What 3M's completed exit, Europe's tightening, and a partial U.S. rollback mean for your PTFE and PVDF sourcing
If you buy fluoropolymers such as PTFE, PVDF, FEP or PFA, the map of who can sell them to you has changed over the past year. Three forces acted on it, and they did not point the same way. A major producer left. Europe tightened its rules. The U.S. partially eased its own. And Japan, which sourcing conversations still treat as a single bloc, has split internally. The new lines on the map do not follow national borders.
What Happened
3M has left. In December 2022, the U.S. industrial group announced that it would stop making all fluoropolymers, fluorinated fluids and additive products based on per- and polyfluoroalkyl substances (PFAS). Annual sales of the PFAS it manufactured were then roughly $1.3 billion, with exit charges estimated at the time at $1.3 billion to $2.3 billion pre-tax. Its annual report on Form 10-K for 2025, filed with the U.S. Securities and Exchange Commission (SEC), states that the company completed its exit of PFAS manufacturing at the end of 2025. Its fluoropolymer range spanned several families, so the effect will appear in specific grades rather than across one product class.
Two qualifications matter to buyers. 3M stopped making PFAS, but PFAS remain in some of its products. The company continues to sell products that contain PFAS sourced through its supply chain. The exit also does not end everything at once. The filing notes that water treatment assets at former PFAS plants will keep treating PFAS from historical production, and that sales and use of products made before the end of 2025 continue in certain cases. Read completion as the end of new supply, not as a sudden gap in the market.
Europe tightened. The Risk Assessment Committee (RAC) of the European Chemicals Agency (ECHA) adopted its final opinion on the universal PFAS restriction on March 2, 2026. The Committee for Socio-Economic Analysis (SEAC) agreed its draft opinion on March 10. Both opinions were published on March 26, alongside a 60-day consultation. That consultation closed on May 25 and drew 3,511 comments from more than 3,200 organizations, with electronics and semiconductors the largest group of respondents.
Industry did not get what it asked for. Producers had argued that high-molecular-weight fluoropolymers should be treated as polymers of low concern, because their environmental fate and exposure differ from the low-molecular-weight substances the restriction is mainly aimed at. That argument was not accepted. A separate claim, that certain PFAS subgroups degrade enough to be excluded from the scope, was also rejected. RAC acknowledged that evidence of fluoropolymers' mobility, bioaccumulative potential and ecotoxicological effects is limited. The committee kept them in scope on life-cycle grounds instead: manufacture and waste are taken to release non-polymeric PFAS, and the use and waste stages may form micro- and nano-sized polymer particles.
Both committees recommended removing or significantly reducing many derogations in the original proposal. Where derogations survive, they will be use-specific rather than sector-wide, and each critical use will be argued on its own technical merits. They will also be conditional, requiring site-specific PFAS management plans, emissions reporting, supply-chain communication, labeling and proof of origin. SEAC expects to adopt its final opinion by the end of 2026. Law firm Covington & Burling expects that the Commission is unlikely to adopt a restriction before the third quarter of 2027.
The U.S. eased, in part. On May 18, 2026 the U.S. Environmental Protection Agency (EPA) proposed rescinding drinking-water standards for four PFAS, while keeping the limits for PFOA and PFOS. The agency also proposed extending the compliance deadline for those two by two years, to 2031. Some state legislatures are moving in the opposite direction: Maine and Minnesota plan near-total product bans by 2032.
Illustration: a pile of fluoropolymer supplies with three streams of light flowing out in different directions, toward a closed factory gate, a binder of rules being tightened, and a valve turned partly open.
Why Now
Three forces: regulatory pressure, liability and demand. News coverage often gives the third less attention.
Regulatory pressure is the visible one. On liability, 3M's decision follows years of litigation exposure tied to fluorochemistry, and the exit still affects its financial results: its 2025 filing cites cost dis-synergies from the exit among the factors compressing margins.
Demand, the third, is rising. Fluoropolymers are hard to replace in semiconductor process equipment, high-frequency boards, millimeter-wave components and battery binders. The reason is not that no other material exists, but that a replacement has to meet several requirements at once: chemical resistance, purity, thermal stability and, in high-frequency uses, dielectric loss. One source of supply has gone just as demand grows for the grades that are hardest to qualify. In other words, PFAS has become a sourcing problem before it is a compliance problem. Supply is falling where demand is rising.
What Most Coverage Misses
PFAS is reported as an environmental and litigation story. There is a standard second framing, in which the West retreats while Japan holds firm. Read as a supply story, that framing is also wrong.
Japan is not acting as one group. Japanese producers have divided by end market.
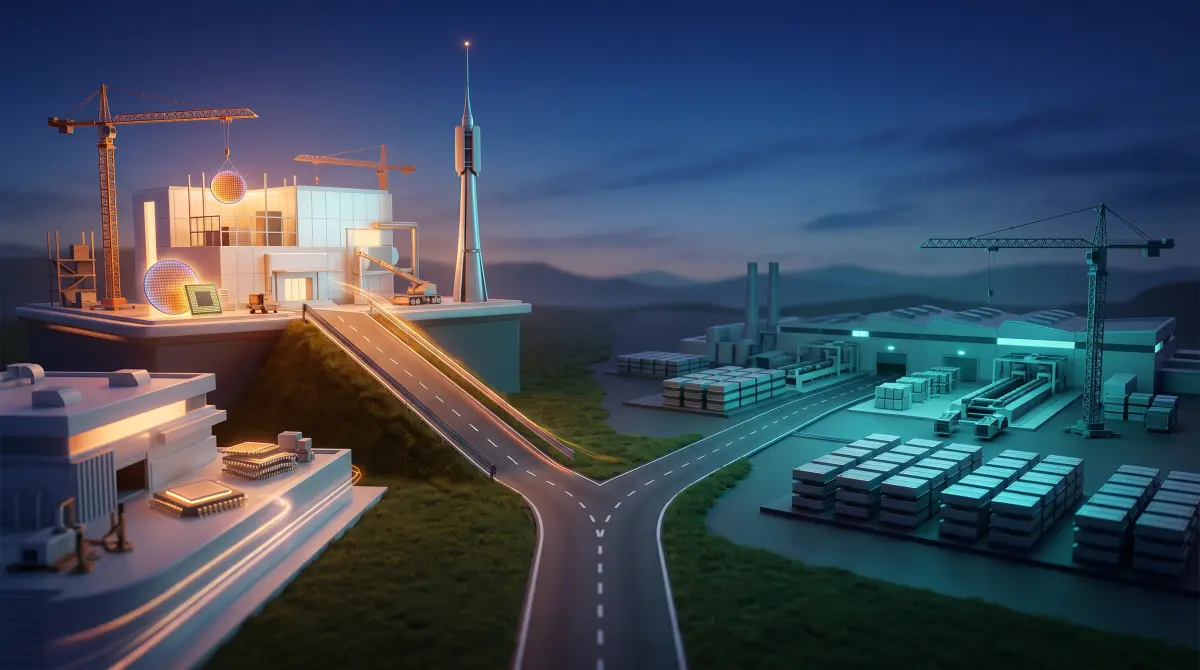
Illustration: one road forks in two. One branch climbs toward a busy semiconductor clean room; the other slopes down toward a quieter battery plant.
Semiconductor and high-frequency: still investing. Daikin's January 2026 sustainability briefing states that its plants already meet the emission-control criteria in the EU draft, and that the company is investing and running R&D before regulations require it in order to secure stable supply. Daikin puts combined sales of five semiconductor-facing high-purity product lines at 90 billion yen ($570 million). In April it disclosed a new perfluoroelastomer (FFKM) plant at Kashima. In July it disclosed PTFE dielectric waveguides for B5G and 6G.
AGC's June 2026 semiconductor briefing targets a doubling of semiconductor-related sales by 2030, from a 2025 base of about 100 billion yen ($640 million), though that figure spans glass and chemicals together. Its fluorine-specific commitments are narrower but more important. AGC is adding fluorochemical capacity at its Chiba works. In July 2025 it launched an SF grade of perfluoroelastomer made with no emulsifier and no fluorinated polymerization solvent, which the company described as ahead of competitors. Takashi Nagai, head of AGC's fluoropolymers division, told the Japanese trade publication MONOist in September 2025 that the grade was developed in response to Europe's PFAS regulatory moves and to demand from semiconductor customers. Daikin completed the equivalent process change for fluoroelastomers in 2025, began selling from 2026, and targets the same switch across its remaining fluoropolymers by around 2030.
To be precise: the restriction covers the manufacture, placing on the market and use of PFAS. Cleaner polymerization does not move a producer outside its scope. It changes two things. The first is how strong a producer's case for a derogation is. The second is the cost of holding one once granted: management plans, emissions reporting, and the volume of non-polymeric PFAS a process generates in the first place. Announcements of added capacity are easy to spot. Once the rules are settled, the producers that can win derogations and keep supplying will be those that have redesigned the process.
Automotive battery: retreating. In April 2026 Kureha booked an impairment of about 34 billion yen ($220 million) on its PVDF business, citing weakness in European and North American electric vehicle (EV) markets and a recovery taking longer than assumed. The charge covers equipment in Japan and China, including equipment still under construction. The new Iwaki plant is now scheduled to begin operation in 2027. The company said that if the business does not return to profit in FY2026, it will consider a fundamental restructuring. Energy storage now accounts for about 20% of PVDF sales, a market Kureha said it had not originally planned for.
It is not that batteries need less PVDF. Kureha's strength is concentrated in binder for ternary automotive cells, and Japan's Nikkei reported that its global share there is around 40%. Lithium iron phosphate (LFP) cells use PVDF binder too. But LFP growth is centered on China and is served largely by Chinese material, and Kureha's own disclosures place LFP-oriented grades among the products it is still developing. The demand did not shrink. It moved into a supply chain Kureha does not yet serve.
Same country, same regulatory exposure, and the trajectories point in opposite directions. What divided them was not nationality. It was end demand.
This series will return to one concept repeatedly. At PlaBase we call it a qualification moat: a customer's process is built around one material, requalification is measured in years, and switching therefore does not happen. The concept explains why incumbent suppliers in semiconductors are so hard to displace.
Kureha's PVDF was protected by switching costs of a similar kind, though never as absolute as in semiconductor process materials. It did not help. European and North American EV volumes disappointed, and growth concentrated in cells built in other supply chains. The moat stayed in place, but the market moved elsewhere. In short: a qualification moat protects you from rivals, not from demand.
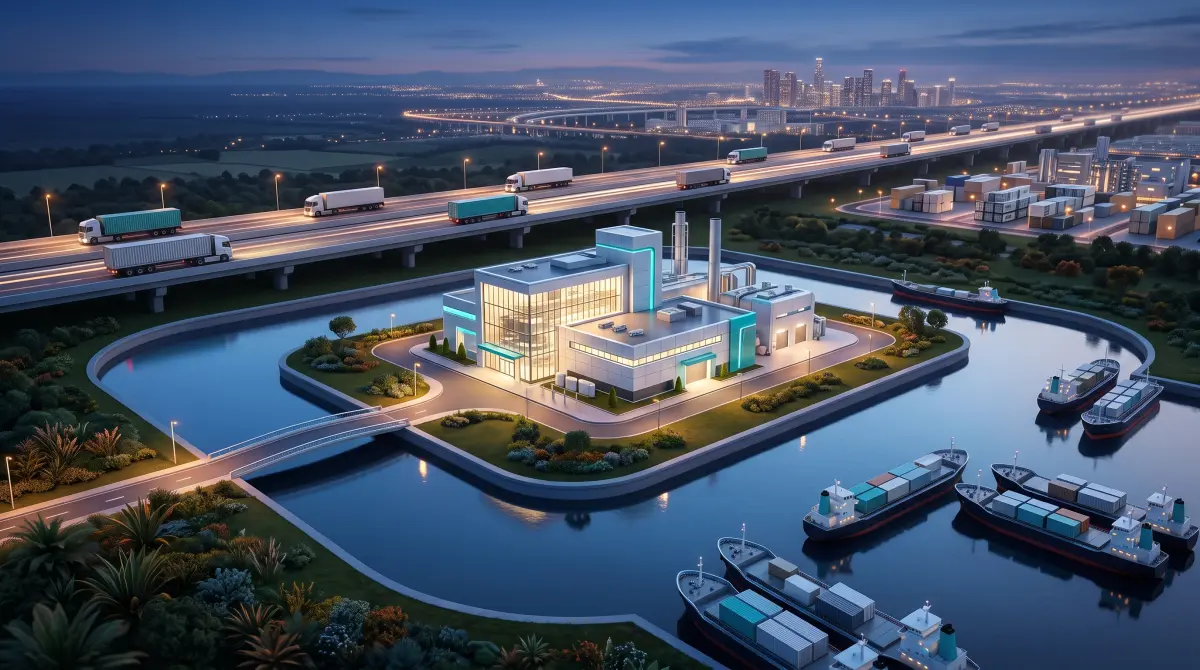
Illustration: a plant on an island protected by a moat. Rival ships stop at the moat, while a highway of trucks bypasses the island toward a distant city.
What This Means for You
If you sell into the EU. Scope is decided by structural definition, not by product name or trade category. Derogations will be argued use by use, and documentation, emissions data and management plans will be the price of continuing. Check now which of your products use which grades, and in what volumes. This is 2026 work, not 2029 work.
If you buy fluoropolymers globally. Replacement capacity for high-purity grades is concentrating in Japan. What is scarce is not fluoropolymer tonnage but tonnage already qualified into your process, and those are two different markets. That distinction also makes concentration here a real risk rather than a theoretical one: a large world capacity figure gives you no alternative if none of it is qualified into your process. So "shift to Japan" is not a sourcing strategy either. Ask which end market your specific grade belongs to, because that is what predicts whether your supplier will still be investing in it in three years.
If you are choosing qualification partners. Engagement while capacity is being built gives you negotiating power that will not be available later. The scarce asset is not polymer capacity. It is qualified capacity.
One caveat against reading this as a Japan story. Japanese producers selling into the EU face the same restriction as everyone else. And from April 2026 Japan made PFOS and PFOA subject to a legally binding drinking-water standard of 50 ng/L combined.
What to Watch
The scope of derogations in SEAC's final opinion, due by the end of 2026. Use-specific derogation is the mechanism that decides whether your application survives, and its width is not yet fixed.
Kureha's FY2026 result. Profit, or fundamental restructuring. This is a key indicator for the battery-facing half of Japan's fluoropolymer industry.
TFA. In June 2026 ECHA's Risk Assessment Committee recommended classifying trifluoroacetic acid (TFA), a degradation product of other PFAS, as toxic to reproduction and as persistent, mobile and toxic. The European Food Safety Authority (EFSA) has since set a consumer health-based guidance value. Fluoropolymers are understood to be a comparatively small source of TFA. Any route from the TFA classification to fluoropolymers would therefore be indirect: through the emissions conditions attached to derogations, through end-of-life handling, or through separate measures on uses whose life cycle releases it. It is worth watching, but the route is not yet clear.
This article is an independent editorial analysis by PlaBase English and does not constitute investment advice. The company strategies and industry developments discussed are based on publicly available disclosures, company statements, and media reports available as of September 2026.